


In this article, medical malpractice insurance expert Max Schloemann explains what physicians should know before buying medical malpractice insurance, including policy types, coverage limits, tail coverage, carrier options, and other key considerations.
Table of Contents
Buying medical malpractice insurance can feel complicated, especially if you are purchasing coverage for the first time. Between policy types, coverage limits, tail insurance, retroactive dates, exclusions, and carrier options, there is a lot to consider.
The good news is that you do not need to become an insurance expert. You just need to understand the terms and coverage features that can have the biggest impact on your protection and your premium.
Here is what physicians should know before buying medical malpractice insurance.
Work With a Malpractice Insurance Broker or Buy Direct?
Physicians can purchase malpractice insurance directly from an insurance company or work with a broker who specializes in Medical Professional Liability Insurance (MPLI).
Working with a specialized broker can make comparison shopping easier. Instead of contacting multiple carriers and completing separate applications, you can typically complete one application and compare several available options.
A knowledgeable broker can also help you evaluate more than price, including:
The goal should be to find the right combination of coverage, carrier quality, and cost for your specific practice.
Claims-Made vs. Occurrence Malpractice Insurance
One of the first decisions to understand is whether your policy is claims-made or occurrence.
Claims-Made Coverage
Claims-made is a common form of malpractice insurance. Coverage generally applies when both:
- The incident occurred on or after your retroactive date.
- The claim is reported while the policy is active.
When a claims-made policy ends, you may need tail coverage unless your new policy provides prior acts coverage.
Occurrence Coverage
Occurrence coverage is based on when the medical incident occurred, hence the term “occurrence.”
If the incident took place while the occurrence policy was active, that policy may respond even if the lawsuit is filed years later.
Occurrence policies, therefore, do not require a retroactive date or tail coverage in the same way claims-made policies do.
TABLE: CLAIMS-MADE vs. OCCURRENCE COVERAGE
| Claims-Made | Occurrence | |
|---|---|---|
| Coverage trigger | Policy must be active when the incident occurs AND when the claim is filed | Policy just needs to be active when the incident occurred |
| Typical premium pattern | Lower in early years, rises as the policy “matures” (step-rated) | Higher flat premium from year one |
| Tail coverage needed? | Yes — if switching carriers, retiring, or closing the practice | No |
| Most common for | Employed / group-practice physicians, cost-conscious early-career surgeons | Surgeons who want cost certainty and no future tail-coverage decision |
Beware the Claims-paid policy form
Besides the claims-made and occurrence policy form, some doctors are insured by a claims-paid policy form, which restricts coverage and flexibility.
In California, many doctors are insured by a Trust on the claims-paid policy form without even realizing there is a difference. The claims-paid form of malpractice insurance can create problems for doctors.
If you have a claim under a claims-paid policy, you are essentially “stuck” with the carrier until the claim is actually paid out. Claims-paid policies are inferior to claims-made and occurrence policies.
What Is a Retroactive Date?
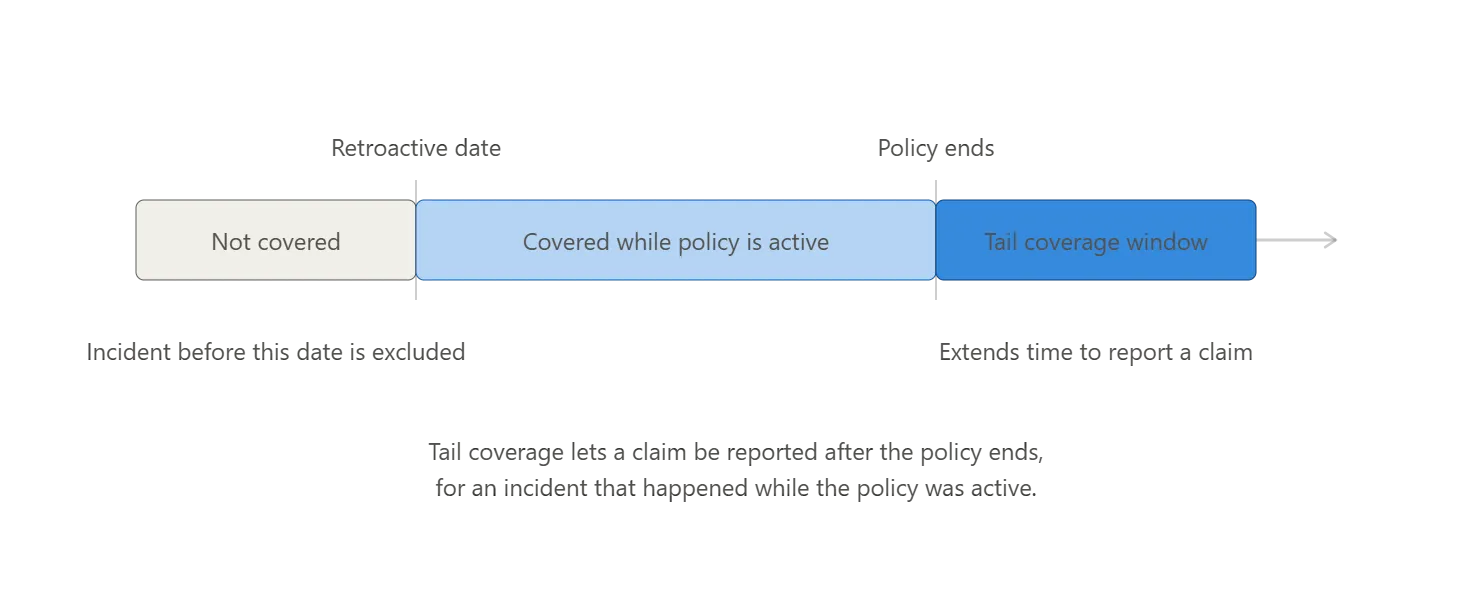
Your retroactive date is a very important aspect of your medical professional liability insurance, if you have a claims-made policy. Your retroactive date, also called prior acts date, is the beginning of the coverage period.
Let’s say your retroactive date is 7/1/2005. Any incidents that occurred before this date will not be covered by your policy.
Your retroactive date will remain the same as long as you maintain claims-made coverage, even if you switch companies. Insurance carriers will cover your prior acts by keeping your retroactive date the same as it was with your former insurance carrier. This allows doctors to take advantage of better pricing without having to buy tail coverage every time they change.
What Is Malpractice Tail Coverage?
Tail coverage, also called an Extended Reporting Endorsement (ERE), allows claims to be reported after a claims-made policy ends for incidents that occurred while the policy was active.
Physicians may need tail coverage when:
Tail coverage can be expensive, which makes it important to understand who is responsible for purchasing it before accepting a job or changing insurance.
Some carriers may provide free tail coverage under certain circumstances, such as qualifying retirement, death, or disability.
What Are Limits of Liability?
Your limits of liability (aka “policy limits”) refer to the amounts the insurance carrier will pay on your behalf in the event of a claim.
In many states, the standard limits of liability are expressed as “$1,000,000/$3,000,000.” The first number (before the “/”) represents the per claim limit. In this example, your insurance carrier would pay up to $1,000,000 per claim on your behalf for a covered loss. The second number is the aggregate limit. With $1,000,000/$3,000,000 limits, your insurance carrier would pay no more than $3,000,000 for all claims within a policy period.
Not all doctors carry $1,000,000/$3,000,000 limits of professional liability coverage.
You should check with a malpractice insurance specialist about which limit level is available, and what most hospitals in your area require for hospital privileges.
Selecting Your Policy Limits
It’s important to select policy limits you are comfortable with, and you should consider any state requirements or requirements that hospitals will require you to carry. If you feel that your limits are inadequate, you can inquire about excess limits.
Are Defense Costs Inside or Outside Your Limits?
This is an important policy detail that is easy to overlook.
Some malpractice policies provide defense costs in addition to your liability limits. Others include defense expenses within the limits.
When defense costs are included within the policy limits, attorney fees and other legal expenses can reduce the amount remaining to pay a settlement or judgment.
All else being equal, physicians generally benefit from coverage that provides defense costs in addition to the policy limits.
Does Your Policy Require Consent to Settle?
Malpractice claims can affect more than your finances. They can also affect your professional reputation.
A consent-to-settle provision determines how much control you have over whether your insurance company can settle a malpractice claim.
Look closely at:
These details can matter significantly if a claim occurs.
Review Your Policy Exclusions
Every malpractice policy contains exclusions.
Common exclusions may involve intentional or illegal conduct, misrepresentation, or professional services outside the scope of the policy.
Physicians working for multiple practices or at multiple locations should pay especially close attention to what each policy covers.
Make sure your coverage reflects:
- Your specialty
- Procedures performed
- Practice locations
- Employment arrangements
- Telemedicine activities, when applicable
- Other professional services you provide
A low premium is not valuable if an important part of your practice is excluded.
What are Premium Payments?
Medical malpractice insurance premiums are quoted in annual terms – a standard policy lasts 12 months. Some carriers require payment in full to make coverage effective. Others, usually admitted carriers, will offer payment terms such as monthly or quarterly.
Some carriers will offer a small discount for payment in full or for automatic recurring payments. MEDPLI can help you identify a malpractice insurance option that will accommodate your preferred payment terms.
Surplus Lines carriers typically require payment in full, especially for a standalone tail policy. If you are buying a standalone tail policy, you are most likely getting a better deal on the premium than what is offered by your employer’s carrier. In exchange for a lower overall price for tail coverage, you will generally have to pay the premium in full.
Missed payments are a leading cause for canceled malpractice insurance policies. MEDPLI recommends setting up your policy on automatic payments if it makes sense to the physician paying the premium. It’s convenient to know the premium is paid, instead of worrying if your check made it in the mail on time.
Types of Malpractice Insurance carriers
1. Admitted Carriers
Admitted carriers are licensed by the state and participate in the State Guaranty Fund, offering an added layer of protection if the insurer becomes insolvent. Examples include Medical Protective, The Doctors Company, Coverys, and NORCAL.
2. Excess and Surplus Lines (E&S)
E&S carriers often insure higher-risk physicians, telemedicine groups, hospitals, and other practices that may not qualify for admitted coverage. They are state-approved but do not participate in the State Guaranty Fund.
3. Risk Retention Groups (RRGs)
RRGs are liability insurers owned by their policyholder members and can offer more flexible coverage. Physicians should carefully review an RRG’s financial stability and ratings before purchasing coverage.
4. Joint Underwriting Associations (JUAs)
JUAs are state-run programs for physicians who have difficulty obtaining coverage in the private market. They may cost more and offer less comprehensive coverage than admitted carriers.
5. Captives
Captives are a form of self-insurance typically created by large healthcare organizations or hospital systems. They are generally not a practical option for individual physicians or small practices.
6. Trusts
Trusts are an alternative to traditional malpractice insurers. Physicians should review the policy form carefully, particularly whether it uses claims-paid coverage, which can be more restrictive than claims-made coverage.
What Are State Guaranty Funds?
The purpose of the state guaranty fund is to protect the policyholder in the event of an admitted carrier’s insolvency, meaning an inability to pay its claims. All 50 states and Washington DC administer a state guaranty fund.
Only licensed insurers, also called “admitted carriers,” must comply with state guaranty laws. State guaranty laws do no apply to unlicensed insurers – such as Surplus Lines Carriers, Risk Retention Groups, and Reinsurers.
For these reasons, admitted carriers are preferable when they can accommodate your healthcare risk.
Malpractice Insurance For Your Specialty
Every medical specialty is unique. Malpractice insurance rates vary by specialty. MEDPLI specializes in medical malpractice insurance for physicians of the followings specialties:
With premiums and indemnity payouts on the rise, MEDPLI is your best ally.
Don’t settle for inadequate coverage or exorbitant rates.
Get a Quote
About the Author
Max Schloemann is a medical malpractice insurance broker helping physicians and surgeons secure Medical Professional Liability coverage. A Magna Cum Laude graduate of Southern Illinois University’s College of Business, he was named Outstanding Management Senior.
Max began his career in 2008 at an industry-leading firm and founded MEDPLI in 2017 to guide private practice doctors and physicians in transition through the complexities of malpractice insurance.
Outside of work, Max, his wife Kristen (a Physician Assistant), and their four kids enjoy the outdoors and attending the kids’ sporting events. Contact Max for malpractice insurance questions.
Latest from the Medical Malpractice Insurance Blog

The Doctors Company completed its acquisition of ProAssurance. See what it means for current policyholders and the malpractice insurance market going forward.

Malpractice Payouts for Florida OBGYNs Are High Florida OB/GYN [...]

Florida Is a Destination for World-Class Neurosurgery [...]

Learn what to consider when buying malpractice insurance, from policy types and tail coverage to limits and carriers. Get a quote from MEDPLI today.